TL;DR
- ✓The monthly premium is the loudest number, but it is only one piece of your yearly cost.
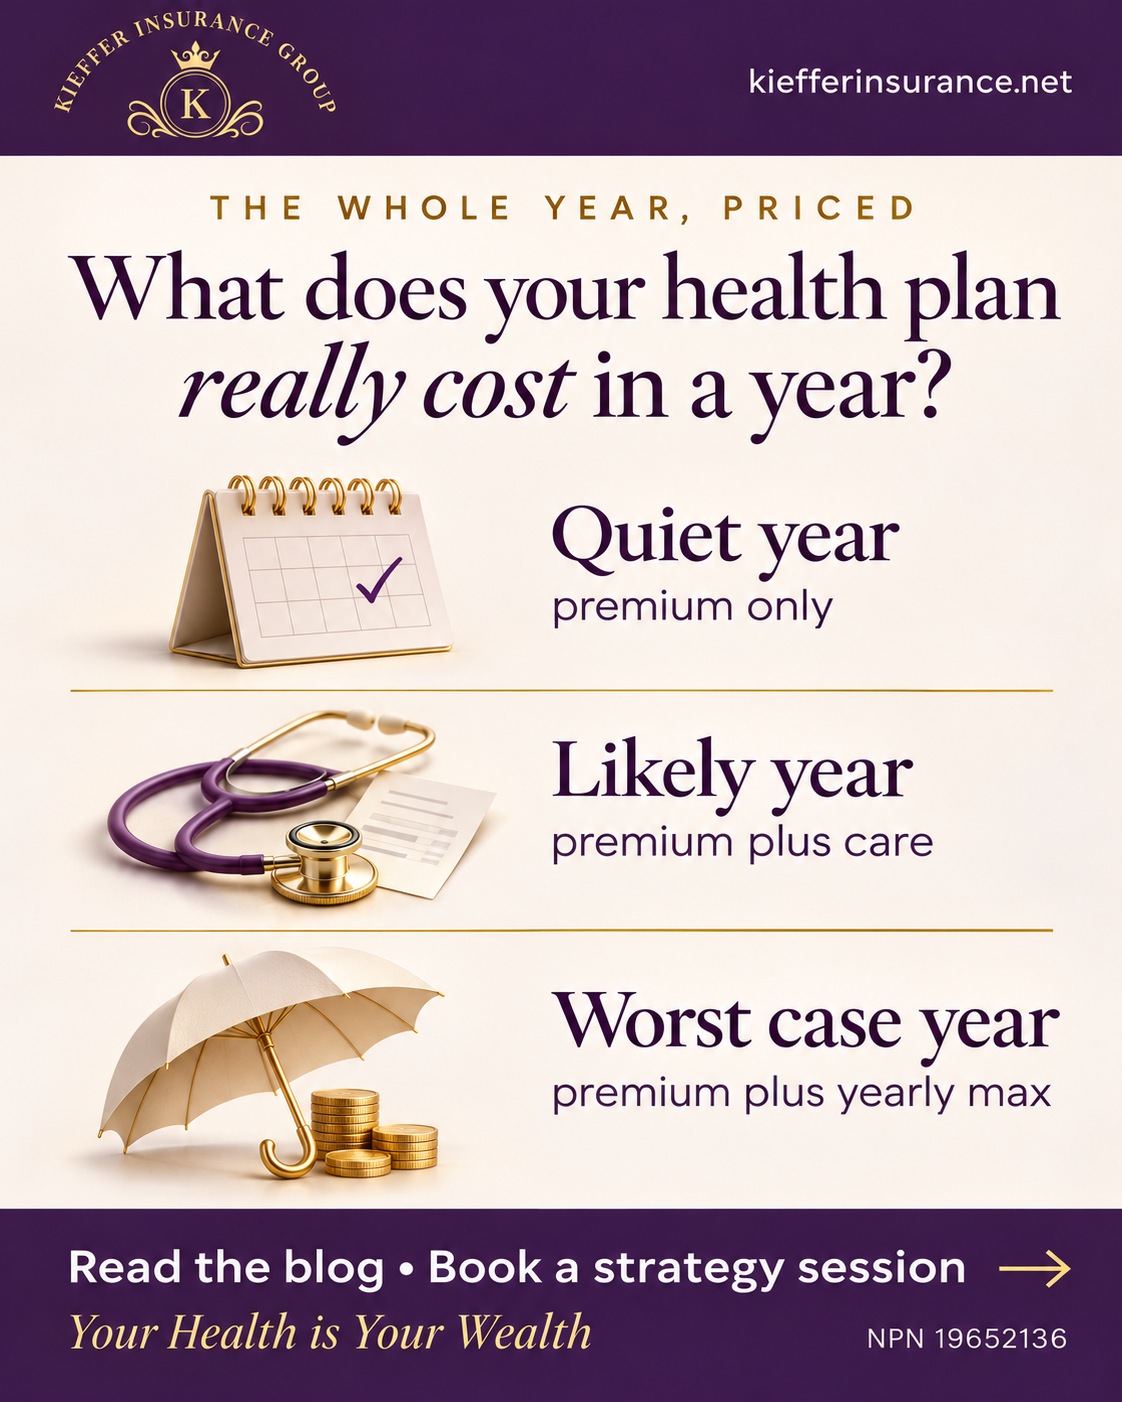
- ✓Price three years for every plan: a quiet year, a likely year, and a worst case year.
- ✓An HSA plan can look "worse" on paper and still win once you count the taxes you may save.
- ✓A good plan review lays all of this side by side, in plain English, before you sign anything.
The short answer: Multiply the monthly premium by 12, then add what you would likely spend on care and what you would spend in a rough year. If the plan is HSA eligible, subtract the tax you may save by funding your HSA. The plan with the best numbers across all three years is your real winner.
Why one number is never enough
Shopping for health insurance by monthly price is like choosing a house by the color of the front door. Lovely door. Tells you nothing about the roof.
When I sit down with a family or a business owner, I never hand over a single price. I hand over a picture of their whole year. Here is what that looks like, using a real private PPO major medical plan I work with often, which rides on a national Cigna PPO network.
A three plan example
These are three private major medical plan options for one adult, using the carrier's October 2026 rate chart. Your numbers will differ based on where you live, who is covered, and how you qualify, so treat this as an example only.
| HSA 6000 | Silver | Gold | |
|---|---|---|---|
| Monthly premium | $640 | $674 | $941 |
| Premium for 12 months | $7,680 | $8,088 | $11,292 |
| Deductible | $6,000 | $5,000 | $3,000 |
| Most you pay for care in a year | $7,000 | $8,700 | $8,700 |
| Office visits | Count toward the deductible | $40 primary, $80 specialist | $35 primary, $55 specialist |
| Quiet year (premium only) | $7,680 | $8,088 | $11,292 |
| Likely year (premium plus your share of about $2,500 of care)* | about $10,200 | about $9,600 | about $12,500 |
| Worst case year (premium plus yearly max) | $14,680 | $16,788 | $19,992 |
| Example HSA tax savings** | about $990 | not HSA eligible | not HSA eligible |
| Worst case year after HSA savings | about $13,700 | $16,788 | $19,992 |
*Example only. The likely year assumes a few visits, a scan, and generic prescriptions. Copay plans absorb some of that, which is why Silver edges ahead in a gentle year. **Example only. Assumes $4,500 put into an HSA (the 2027 self only limit) at a 22% federal tax bracket. Your savings depend on your bracket and your state.
Look at what happens. The Gold plan "feels" safest with its low deductible, yet it costs the most in every single year. The HSA 6000 is not the cheapest in a gentle year, but in a rough year, once the HSA savings are counted, it comes out over $3,000 ahead of Silver and over $6,000 ahead of Gold.
The HSA part most people skip
A Health Savings Account lets you set money aside for medical costs before taxes, grow it, and spend it tax free on qualified care. Three quiet superpowers:
- ✓You may save tax on the way in. Every dollar you put in may lower your taxable income.
- ✓It can keep growing. Unused money rolls over every year. It never disappears.
- ✓You may spend it tax free on qualified care, now or decades from now.
So when I compare plans, I do not stop at the premium. I show the possible HSA savings right in the comparison, because that can be real money back in your pocket. Good news for marketplace shoppers too: starting in 2026, bronze and catastrophic marketplace plans count as HSA eligible, which opens this door for many more people.
What a deep dive review actually covers
Whether you work with me or not, here is what a thorough review should give you:
- ✓Three years priced, not one. Quiet, likely, and worst case, side by side.
- ✓Your doctors and prescriptions checked on every plan, not just the one on sale.
- ✓Tax math included. Possible HSA savings, and for business owners, how premiums may fit into your business.
- ✓Options beyond the marketplace. Private PPO plans, and when they make sense for 1099 earners and small business owners.
- ✓A clear recommendation with reasons, written so you could explain it at the dinner table.
That is the difference between someone who sells a plan and a strategist who helps you plan. The first one fills out a form. The second one asks, "What does your year look like?"
Frequently asked questions
What is the best way to compare health insurance plans? Price each plan for a quiet year, a likely year, and a worst case year. Add 12 months of premium to your expected care costs and to the yearly out of pocket maximum, then subtract any HSA tax savings you may qualify for.
Is a high deductible HSA plan worth it? Often, yes. HSA plans usually carry lower premiums, a capped worst case, and possible tax savings on every dollar you contribute. If you can set money aside, the math frequently beats a richer copay plan.
Are bronze plans HSA eligible in 2026? Yes. Starting in 2026, bronze and catastrophic marketplace plans count as HSA eligible, so many more people can open and fund a Health Savings Account.
Want your own whole year picture?
If you would like to see your plans priced out like this before 2027 begins, I would love to walk through it with you. No pressure, just clarity.
Book your 2027 strategy session or call 561-660-9894.
Rates shown come from an October 2026 carrier rate chart for one adult and are for education only. Eligibility, availability, and pricing vary. This is not tax advice; check with your tax professional about your HSA.
Get Christine's Insights Every Wednesday
One short email a week with the newest article on health coverage, taxes and benefits for 1099 pros, families and small business owners. Unsubscribe anytime.